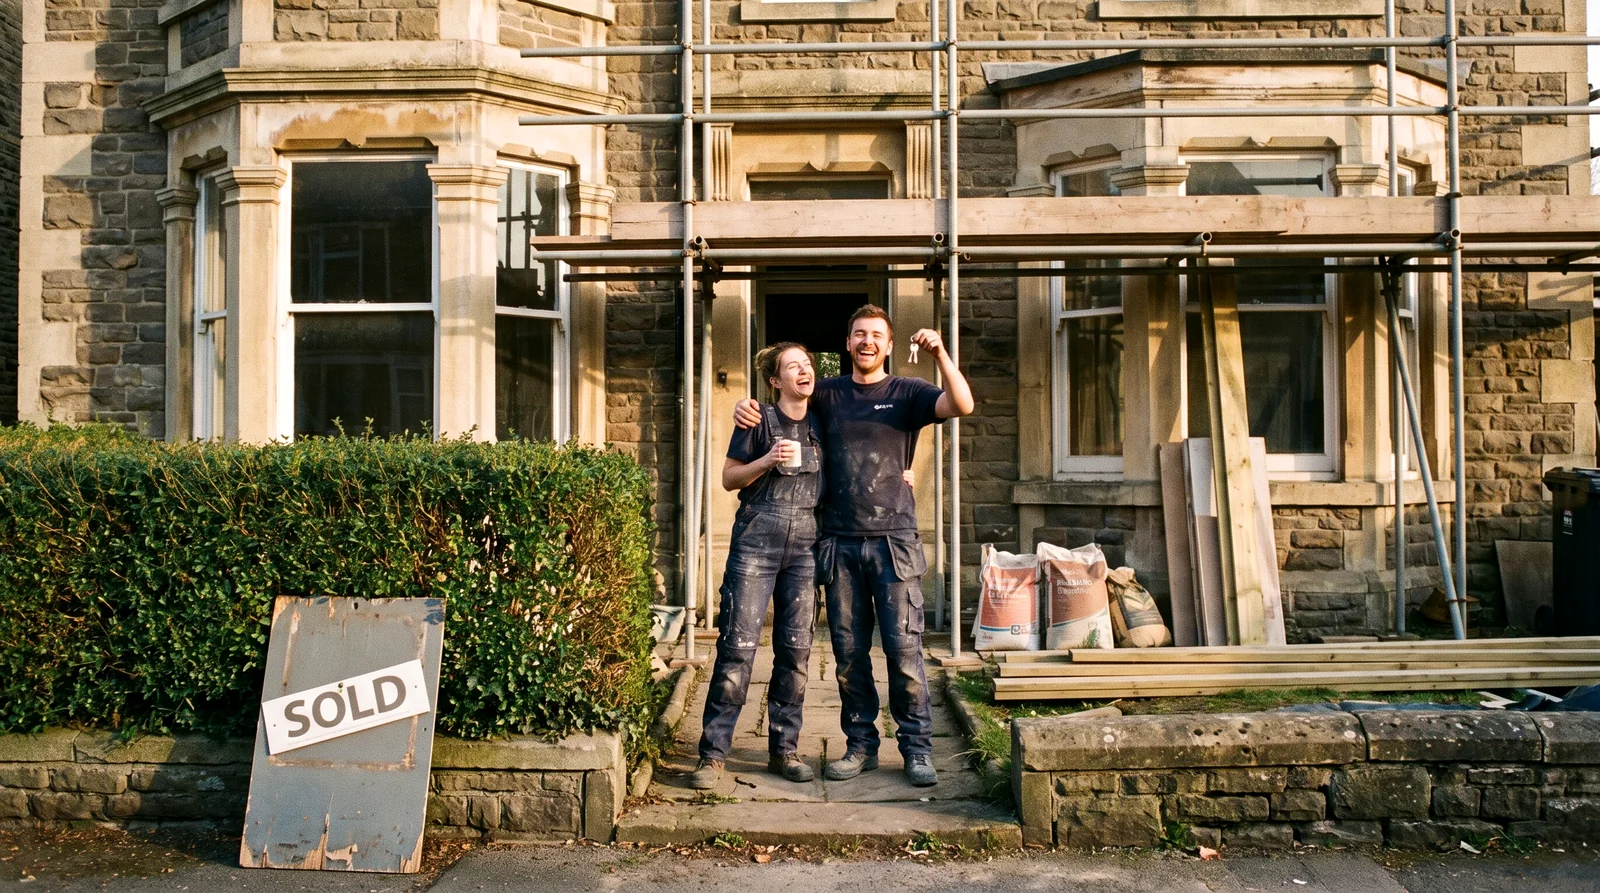
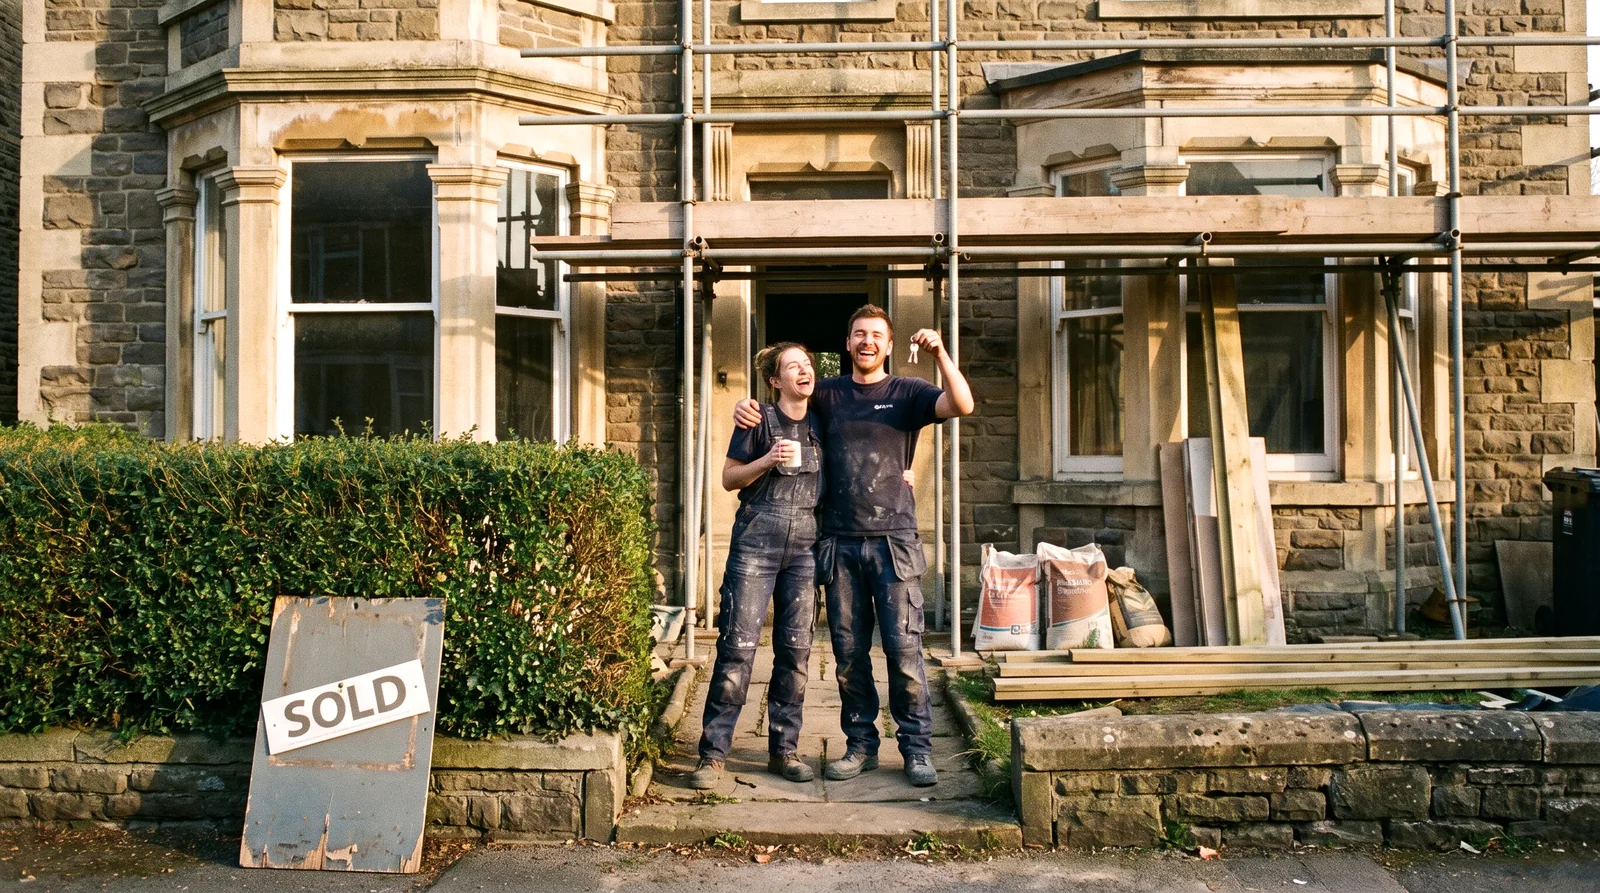
Bridging finance is short-term, secured lending designed to be repaid quickly, usually within twelve months, from a defined source such as a sale or a longer-term mortgage. It is fast and flexible, and it is expensive. Used for the right problem it is invaluable. Used as a substitute for planning it is a trap.
What it is actually for
Bridging solves timing problems. Buying at auction, where completion is required in twenty-eight days. Breaking a chain when your sale slips but your purchase cannot wait. Buying a property no ordinary mortgage will touch yet, because it has no kitchen or bathroom, then refinancing once it is habitable. In each case the loan bridges a short, specific gap.
The exit is the whole thing
Every bridging loan needs a credible exit, the plan to repay it. A sale that is already agreed, or a mortgage offer lined up to refinance onto. Lenders underwrite the exit as much as the property, and rightly so, because a bridge with no clear way out becomes an expensive problem fast. If you cannot say precisely how and when it will be repaid, it is not the right tool.
The cost, plainly
Bridging is priced monthly, not annually, and carries arrangement and exit fees. Over a few months on the right deal that cost is worth paying for the opportunity it unlocks. Over a dragging, ill-planned eighteen months it can erode the whole gain. The maths only works when the loan is short and the exit is real.
A bridge is worth paying for when it is short and the way off it is certain.
Where advice helps
The bridging market is broad and specialist, and terms vary widely between lenders. The right structure depends on the property, the exit and the timescale. Bridging is secured on property, which may be at risk if the loan is not repaid, so the plan matters more than the rate. Some forms of bridging are not regulated by the Financial Conduct Authority. We assess whether bridging is genuinely the right answer before arranging it, and where it is not, we say so.